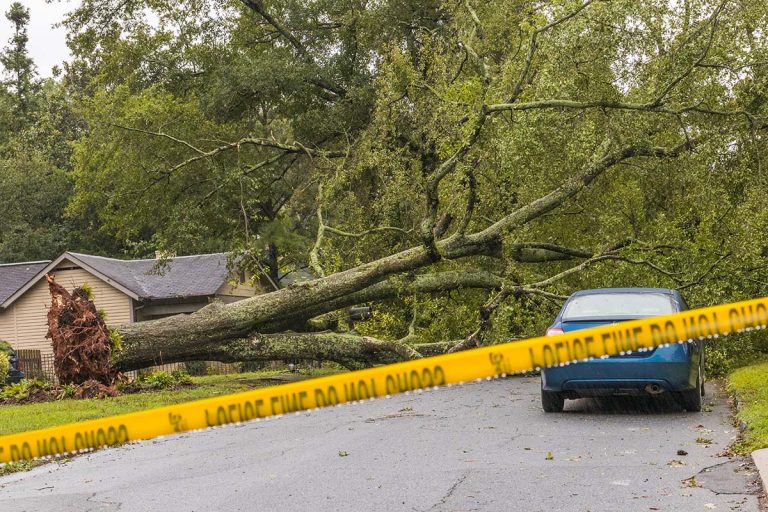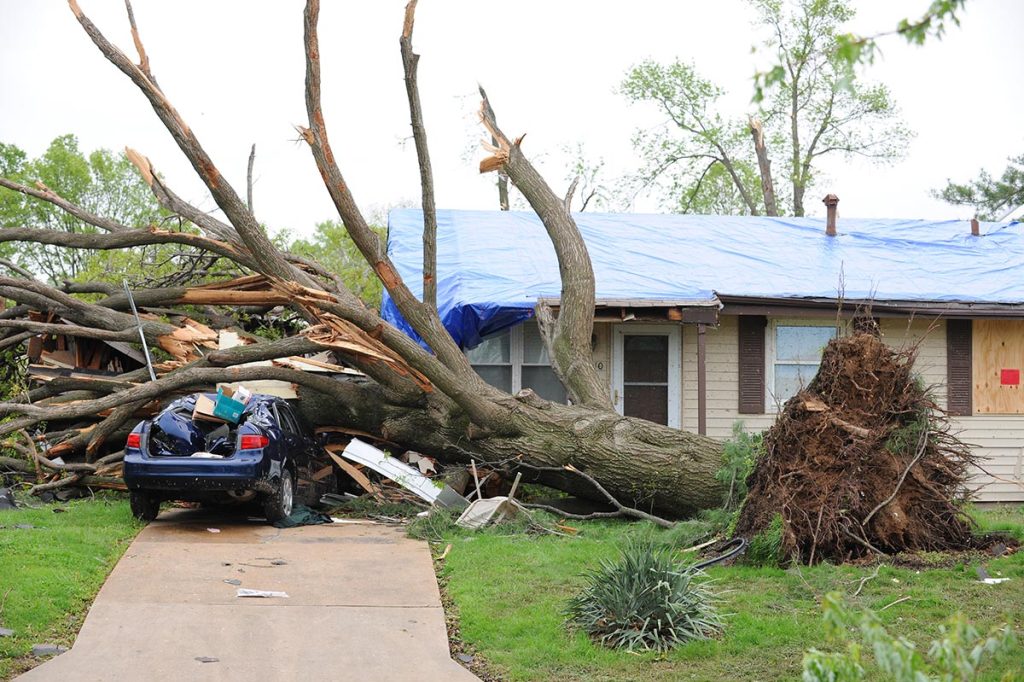
Fort Lauderdale hurricane property damage insurance claims lawyers tell how residents can receive full claim amount after hurricanes
It’s been more than a month since hurricane Irma devastated parts of Florida and some in the Fort Lauderdale area are still decluttering from the leftover debris. While the piles of trash and dead tree branches and limbs pile up in many municipalities, your life is also still mired in mayhem, not the least of which is the way you may have been treated by your insurance companies. They believe they have weeded out your problem. You’re still ankle deep in muck.
Property insurance holders in southeast Florida, and in particular Fort Lauderdale, should pay attention and heed some good advice from the legal experts. Hurricane season, which brings with it high winds, rain, tornadoes and damage, isn’t over. We want you to prevail the next time you might be filing a property damage insurance claim.
First, it’s understandable that you may still be feeling overwhelmed by what you have faced and are still facing when it comes to your property damage claim in the aftermath of Irma. You may still need to repair and replace – and the insurance company isn’t helping you to achieve your goal, especially if you have substantial loss, reflected in the high amount of your insurance claim.
Remember: While you may be unfamiliar with insurance laws – maybe this is your first time filing a claim in Fort Lauderdale – you do have rights.
First of all, you should read your policy’s “Declaration Page,” which details the various categories that comprise your policy. Take some quiet time now and read the policy as thoroughly as you can to give yourself the basics of what it contains and what your rights are, as far as how much you can seek in the areas of dwelling replacement, debris removal, trees and building code compliance. Don’t simply rely on the insurance company’s adjuster to compute what you are owed – you could end up not being paid the full amount.
Be particularly mindful of the following in reviewing your insurance policy:
Temporary pet boarding and temporary rent following the loss of your home
Gas and mileage expense, should you need to travel further to carry out your daily activities, such as grocery shopping, work, etc.
Food, especially if you are in a hotel with no cooking facilities. Submit restaurant meal receipts to the insurance company, then relocate your family as quickly as possible to a place that is fully equipped, otherwise, you could end up using monies for food that would otherwise go to temporary rent.
Wondering what, exactly, you are covered for, and can seek reimbursement for? Be sure to ask whether you are covered for additional living expenses. In addition, you may even be able to acquire a living expense payment in advance, although these monies generally are given as reimbursements.
Most times, it takes between 18-24 months to repair and/or rebuild a damaged home after a loss event such as a hurricane.
You can look to your policy to seek other answers as far as what sort of damage is covered following a hurricane. When it comes to debris, the homeowner is the one responsible for getting it cleared, although you may be able to receive additional coverage for debris removal. Read your policy carefully – the amount you need cleared could exceed the amount of your coverage.
House and property damage, debris removal and other items associated with the aftermath of a storm like Irma in Fort Lauderdale make navigating through the insurance web tricky. Chances are, your home is your biggest asset. Insurance companies are most likely not going to decide in favor of you, the homeowner, and will interpret their policies according to what’s best for them. Don’t easily accept what the insurance company says you’re entitled to. After all, you are the one who pays regularly on your insurance policy, thinking the insurance company will make good on its contract with you and pays you what you are entitled to. Think ahead and make sure you have coverage for a variety of items.
Generally, the following are the most problematic for property owners in the wake of a storm:
- Being underinsured – not having enough insurance coverage
- Delays in payment
- Confusion over what is covered
- Lower estimates than expected and settlement offers
- An adjuster who is difficult to work with
- Differences of opinion on the scope and value of losses
Whether you are new to filing a claim from a hurricane or find yourself overwhelmed this time around, you should contact on a competent and knowledgeable Fort Lauderdale property damage insurance claims attorney, one who has navigated through the insurance quagmire and understands what can go right – and wrong. Always be careful – scam artists come out of the woodwork to prey on people following disasters.
In the wake of Irma, you may have been swept away by what you perceived were your rights as a property owner versus what you really received from your insurance company. A Fort Lauderdale property damage insurance claims attorney can come to your rescue. Know your rights.